In Flex HRM Payroll, we distinguish between Working time account (ATK) and Shortening of working hours (ATF) as follows:
- Working time account (ATK)
When, according to the collective agreement, a certain percentage of earned wage is allocated to a working time account. In some collective agreements, this is referred to as working life time. - Shortening of working hours (ATF)
When, according to the collective agreement, time is allocated into a time bank for each hour worked. Usually, a certain number of minutes are allocated per fully worked week.
There are many different rules regarding AKT/ATF in various collective agreements. It is therefore important that you are aware of how your specific collective agreement regulates this. To process the rules for different agreements, you create different ATK / ATF agreements in HRM Payroll, where you configure the settings. You do this through Administration > Settings > Payroll > ATK / ATF agreement. After that, you link an agreement either to the employee or to a personnel category.
It may also be the case that instead you have/need a customised solution using time transactions, pay codes and accumulators (e.g. for agreements where the qualifying and withdrawal periods coincide, the function with ATK / ATF agreement cannot be used as these only calculate with a delayed qualifying period.)
Please note!
If you are unsure how to configure your ATK or ATF agreement so that it complies with your collective agreement, we recommend that you seek assistance from a consultant from Flex Applications.
Each month, an allocation is made based on the percentage rate or number of minutes per week specified in the ATK / ATF agreement.
Different principles for qualifying and withdrawal
There is a wide variety in collective agreements regarding qualifying periods and withdrawal periods for ATK and ATF.
For both ATK and ATF agreements, the cash principle applies; that is, payroll transactions in the payroll period are the specification for the qualifying amount for that same month.
For example, for ATF it is the worked time in March, fetched and processed in April's payroll run, that forms the basis of the calculation for qualifying for April.
For ATK, in the same way, allowances/deductions processed in April's payroll run are the specification for the calculated qualifying amount for April.
Shortening of working hours (ATF)
For ATF, there are mainly two different variants. Either you accrue and withdraw time on an ongoing basis, similar to a comp or flex balance. If you have this type of handling, this is managed in Flex HRM Time as a balance with event functions for qualifying.
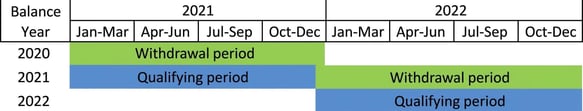
The other variant is that you earn ATF hours over a period of 12 months, and during the following 12 months, you can withdraw these hours as time off. Sometimes, it may be possible for the employee to choose to have the accrued hours paid as paid compensation or allocated towards pension.
Example:
Qualifying takes place during 2021 (1 January – 31 December). The withdrawal period is during 2022.
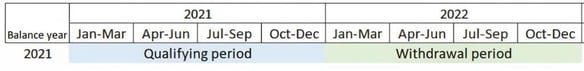
When the withdrawal period begins, a new qualifying period starts at the same time. The image below shows the different years managed in parallel at various points in time.
Working time account (ATK)
For ATK, you always have a qualifying period of 12 months when money is allocated to a working time account. After that, there is a 12-month withdrawal period which usually starts some time after the end of the qualifying period. The period between the end of the qualifying period and the start of the withdrawal period is to give time for administration of the employee's choice, as it is usually possible for the employee to choose whether to withdraw the money from the working time account as either paid compensation, paid time off, or as extra pension provision.
Example:
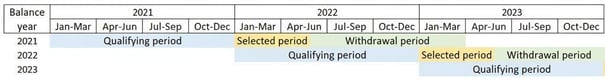
Qualifying takes place during 2021 (1 January – 31 December). After that, the employee has until 31 March to decide what to do with the accrued money. If the employee chooses paid time off, the withdrawal period is from 1 April 2022 to 31 March 2023.

When the selected period begins, a new qualifying period starts simultaneously. The image below shows the different years managed in parallel at various points in time. During the period January–March 2023 in this example, there are balances for three different qualifying periods at the same time. There is a withdrawal period for what was earned in 2021, a selected period for the money earned in 2022, and at the same time qualifying for 2023 has started.
Related articles:

How does the ongoing management of ATK and ATF work?
What are the annual procedures for the working time account (ATK)?
Please note: This article is AI-translated. This means that linguistic errors or misunderstandings may occur.